A Leather Tale
For decades, Bangladesh has occupied a unique paradox in the global leather trade. On one hand, it is one of the world’s largest producers of raw hides and semi-processed leather, backed by a deep cattle supply base, low labor costs, and proximity to major shipping routes. On the other hand, despite enormous manufacturing capacity, Bangladesh’s leather export earnings have remained stubbornly modest hovering around USD 1-1.2 billion annually, far below the country’s true potential and nowhere near the explosive success seen in garments.
Industry veterans often ask a painful question:
If Bangladesh became a USD 45+ billion garments powerhouse, why hasn’t leather followed the same path?
The answer is not factory scale.
It is not access to raw material.
It is not even cost competitiveness.
The overwhelming barrier is compliance like environmental, chemical, wastewater, worker safety, traceability, LWG certification and the inability of the sector to adapt quickly enough to shifts in global regulatory expectations.
This article presents a consultant-style breakdown of how compliance evolved from a “nice-to-have” into the single most decisive factor driving buyer decisions, restricting market access, and limiting Bangladesh’s ability to capture billion-dollar contracts.
The Lost Promise of Bangladesh Leather
In the 1990s and early 2000s, Bangladesh emerged as an attractive sourcing base for footwear uppers, finished hides, and low-to-mid tier leather accessories. Hazaribagh, Dhaka had become the nerve center of tanning operations chaotic but hyper-productive.
At its peak:
- Over 200 tanneries operated in Hazaribagh
- The cluster employed more than 30,000 workers
- Exports reached buyers across Italy, Germany, Spain, China, Japan, and Eastern Europe
Yet behind this rapid expansion ran a dangerous contradiction:
- No central effluent treatment system
- River sludge dumping directly into Buriganga
- Unregulated chromium discharge
- Unsafe chemical handling
- Minimal traceability or wastewater testing
For years these issues were overlooked by international buyers, largely due to the overwhelming price competitiveness of Bangladeshi leather.
But the global market changed faster than Bangladesh did.
The Compliance Revolution
Post-2010, international environmental and social governance rules tightened dramatically:
- EU buyers shifted toward REACH chemical regulations
- Footwear brands adopted Leather Working Group (LWG) sourcing restrictions
- Traceability requirements became embedded in audit cycles
- Carbon footprint accounting emerged as a purchasing criterion
Bangladesh, still operating primarily through uncontrolled tannery clusters, suddenly became a compliance risk location.
In 2017, the government relocated tanneries from Hazaribagh to the newly developed Savar Tannery Industrial Estate (TIE) with the promise of:
- Modern Central Effluent Treatment Plant (CETP)
- Zoning separation of hazardous discharge
- Cleaner production lines
- Better international audit access
The physical relocation occurred but the compliance revolution did not immediately follow.
Savar: Infrastructure Shift Without Behavior Change
The Savar Tannery Estate was designed as a path to redemption:
- 200+ tanneries relocated
- Integrated wastewater plants installed
- Chemical storage zones demarcated
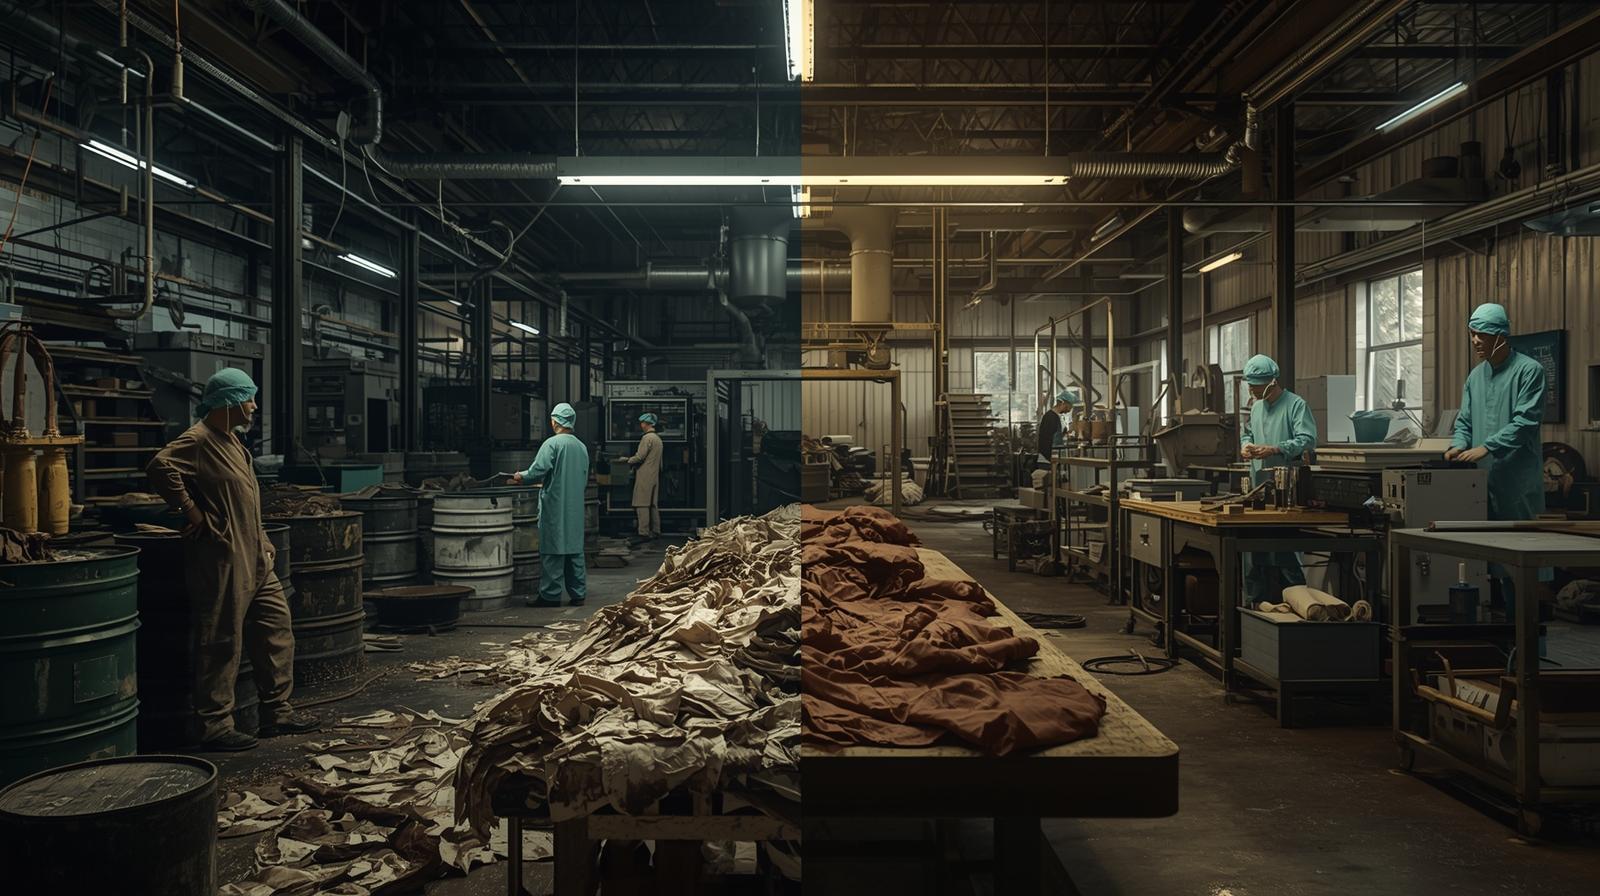
But execution proved inconsistent. The problems:
-
CETP Under-capacity
The treatment plant initially struggled to handle full production load:
-
- Sludge management issues
- Inconsistent chemical balancing
- Delayed heavy metals neutralization
Partial discharge failures meant environmental compliance audits frequently failed.
-
Individual Factory Weakness
Buyers assess factory-level compliance, not estate-level promises.
Many tannery owners:
-
- Continued informal chemical procurement
- Used outdated machinery incompatible with clean-tanning workflows
- Failed traceability documentation audits
LWG assessors repeatedly flagged factories for:
-
- Lack of waste tracking
- Poor worker safety compliance
- Substandard water testing
The Real Buyers’ Problem
For European, Japanese, and North American brands, Bangladesh did not represent a production risk, it represented a reputation risk.
A single toxic discharge scandal can destroy brand value built over decades.
Thus, sourcing teams shifted decisions toward compliance stability over price.
Countries like:
- Vietnam
- India
- Turkey
…began capturing contracts that Bangladesh underpriced because their compliance standards consistently passed LWG Gold or Silver certification.
What Compliance Really Means Today
Compliance is no longer one checklist. It is an integrated operating framework involving:
-
Environmental Compliance
- Wastewater chemical oxygen demand (COD) testing
- Chrome recovery systems
- Sludge disposal certification
-
Chemical Management
- ZDHC compliance
- Banned substance testing
- Full material safety data tracking
-
Traceability
- Source hides origin mapping
- Batch production records
- End-to-end transparency logs
-
Worker Safety
- PPE provision
- Occupational ventilation standards
- Fire and emergency exit certification
Failure in any single module disqualifies the supplier regardless of price advantage.
Case Example – The Bonded Warehouse Misstep
A major Bangladeshi export-focused tannery invested millions of dollars into building an in-house warehouse intended for bonded operations, expecting duty deferrals and working-capital savings.
However:
- Regulatory restrictions made bonded warehouse licensing difficult for chemical tanning operations.
- The facility remained underutilized.
- The expected financial edge never materialized.
Lesson: Infrastructure investment without regulatory clarity produces capital traps a pattern repeated throughout the sector.
Case Example – The Tannery Client Warehouse Search
A multinational tannery company exploring Bangladesh as a leather-processing hub sought to establish compliant warehousing in the southern region.
Their requirement:
- Chemical handling compliant warehouse
- Traceability-secure bonded storage
- Environmental clearance status
Despite months of searches:
- No warehouse matched both regulatory compliance and operational practicality.
- Potential leasing locations failed zoning and environmental approvals.
- The investment collapsed.
Lesson:
Foreign buyers increasingly abandon Bangladesh projects not for capacity reasons but because aligned compliance real estate simply doesn’t exist when they need it.
Comparative Market Position
| Country | LWG-certified tanneries | Buyer confidence | Regulatory stability |
| Vietnam | High | Strong | Stable |
| India | Moderate-High | Strong | Improving |
| Turkey | High | Very strong | Mature |
| Bangladesh | Low-Moderate | Weak | Inconsistent |
Why Compliance Is a Billion-Dollar Barrier
Analysts estimate that Bangladesh could easily expand leather exports toward USD 4-5 billion annually if compliance stabilized.
The barriers blocking this growth:
-
Certification Bottlenecks
-
- Only a fraction of tanneries has meaningful LWG approval.
- Re-audits and corrective action costs pressure cashflow.
-
Capital Misallocation
-
- Investments prioritize machinery volume over process quality.
- Compliance upgrades remain secondary after production expansion.
-
Audit Literacy Gaps
-
- Factory management lacks familiarity with Western regulatory protocols.
- Audit documentation often fails procedural tests, not production tests.
-
Weak Industrial Ecosystem
-
- Chemical waste recycling vendors are limited.
- PPE compliance supply chains remain fragmented.
- Independent testing labs are overloaded.
Buyers Want Factories, Not Speeches
Global brands no longer consider government assurances. They operate on one principle:
“Certify first – source later.”
Bangladesh has made macro-level commitments to environmental sustainability, but global buyers anchor decisions at the factory floor:
- Does this production line pass trending audits?
- Will traceability records stand legal review?
- Does effluent compliance match EU standards weekly, not yearly?
Too often the practical answers remain uncertain.
The 2025-2030 Outlook
Industry consultants anticipate gradual but substantial progress:
- Increased CETP efficiency upgrades
- Factory consolidation (fewer but larger licensed tanneries)
- Rise of compliance-focused industrial parks
Projected outcomes:
- Export earnings doubling within 5-7 years
- Movement toward finished leather goods rather than raw hides
- Manufacturing of higher-margin footwear contracts
However, none of this will materialize without consistent compliance enforcement, not seasonal crackdowns.
The choice is no longer academic. It is existential.
Bangladesh’s leather sector is not blocked by lack of talent. It is blocked by process inertia.
Compliance is not a cost, it is the market entry fee in modern global trade.
Until the industry internalizes this reality, Bangladesh’s leather exports will remain capped beneath their true potential, trapped between overcapacity and under-credibility.
The industry stands at a crossroads: Xtradegrok
- Continue commodity tanning: low margin, fragile demand.
- Or migrate toward sustainable-certified production: fewer factories, higher contracts, larger market share.
References
- Leather Working Group (2024) LWG Environmental Audit Protocol Overview.
- The Business Standard (2024) Why Savar tannery estate still struggles with compliance. Dhaka: TBS.
- The Daily Star (2023) Bangladesh’s Leather Sector: Compliance hurdles limit growth. Dhaka.
- European Commission (2023) REACH Chemical Regulations – Leather Products. Brussels.
- World Footwear Yearbook (2024) Global Leather Certification Trends. Milan.