The Question Every Importer Asks and the Uncomfortable Answer
If there is one question that keeps importers awake at night in 2025, it’s deceptively simple: “Why are freight rates still so high when the pandemic is long over?”
Ask any procurement manager in Dhaka, any sourcing agent in Hamburg, or any supply chain director in Los Angeles. They’ve survived port closures, container shortages, and record-breaking spot rates. They were promised relief. Yet, as we move deeper into 2024 and look toward 2025, relief feels like a mirage. A 40-foot container from Shanghai to Rotterdam still costs over $3,500 on the spot market triple what it was a decade ago.
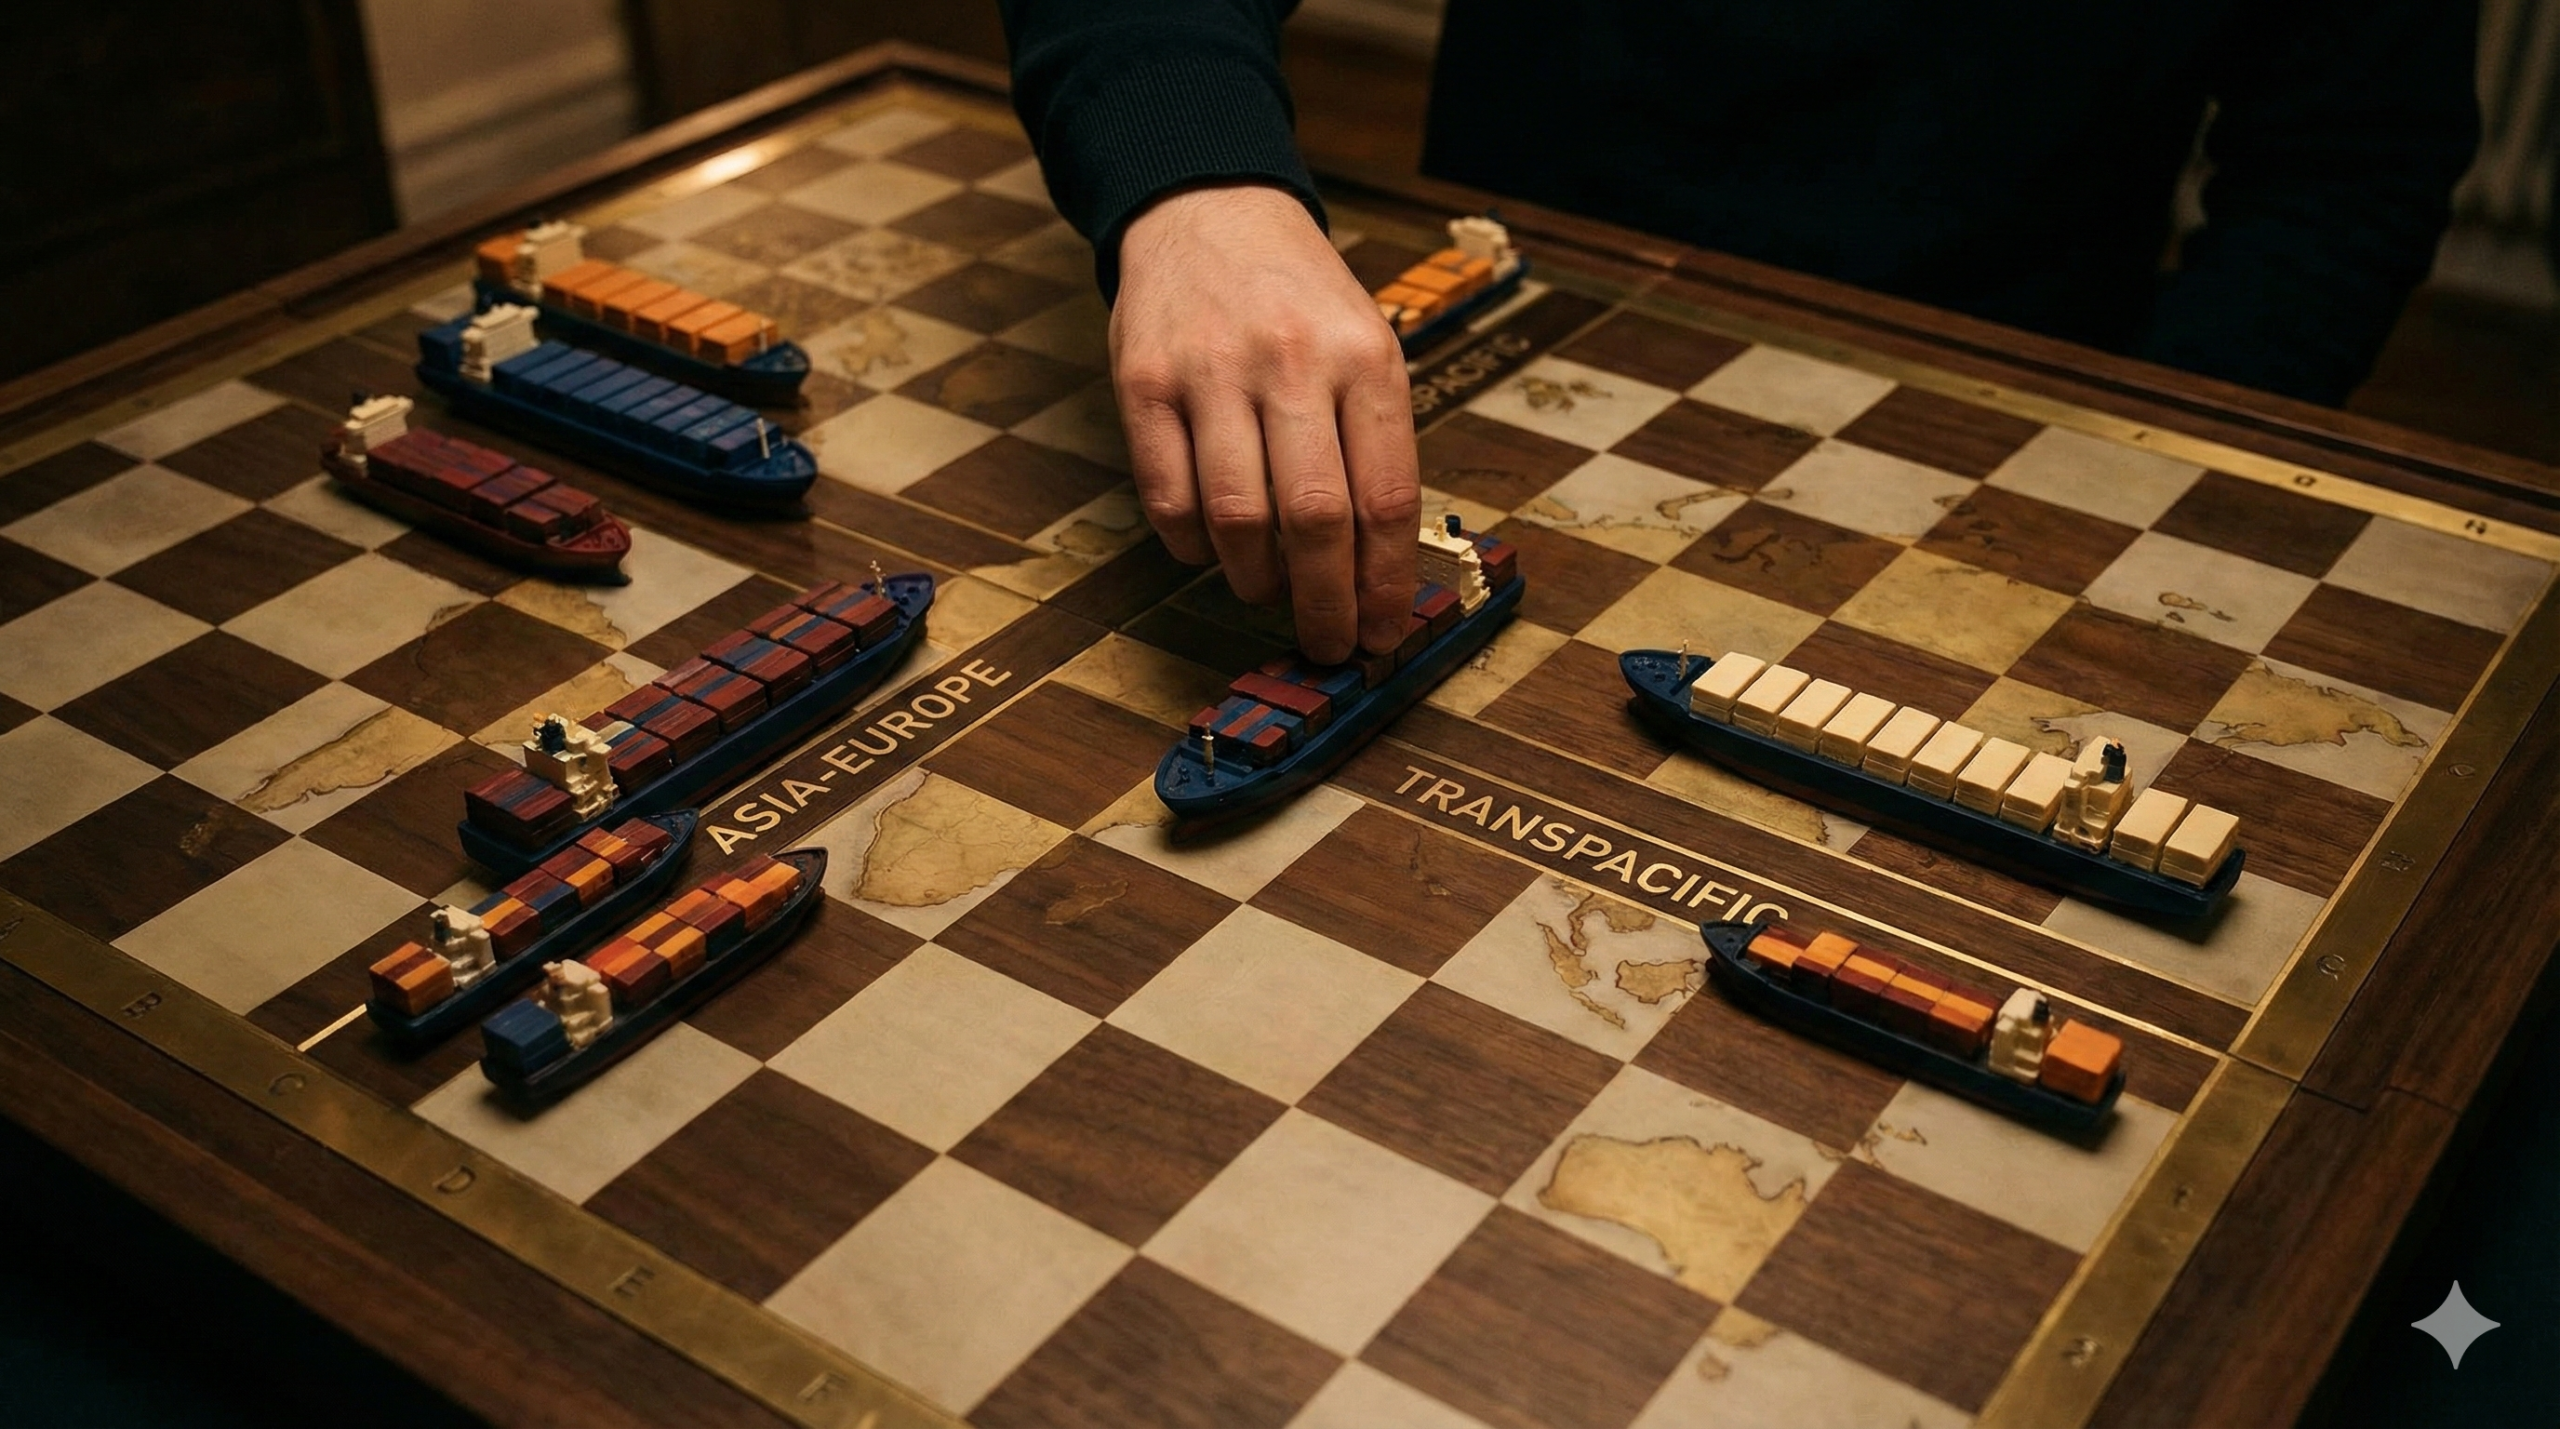
The uncomfortable truth is that the answer isn’t found in simple supply and demand charts. Freight does not operate as a classic free market. It operates more like a global chessboard controlled by a handful of immensely powerful players the ocean carriers who collaborate, coordinate, and have systematically engineered an ecosystem where competition is managed, not unleashed.
The biggest supposed shake-up of the decade the dissolution of the 2M Alliance (Maersk and MSC) was heralded as the dawn of a new competitive era. Instead, it triggered a sophisticated restructuring that has, paradoxically, tightened the carriers’ grip on global trade flows. What emerged wasn’t chaos, but a new, more disciplined order: MSC as a sovereign giant, and Maersk forming the “Gemini Cooperation” with Hapag-Lloyd.
Behind the scenes, the fear whispered in logistics conferences is becoming reality: a consolidated global ecosystem where alliances, joint operations, and digital synchronization create a de-facto cartel environment. The rates didn’t stay high by accident. They stayed high because the architecture of global shipping is now designed for carrier profitability first, and shipper cost-saving second.
This article pulls back the curtain on that architecture. It’s the story of the new 2025 landscape unfiltered, updated, and explained through the lens of a Bangladeshi exporter or a European retailer who simply needs to get goods from point A to point B without being bled dry.
Part 1: The Post-2M World A Restructuring, not a Revolution
The Great Disruption That Wasn’t
For nearly a decade, the 2M Alliance between Maersk and MSC was the backbone of the world’s major trade lanes, setting the rhythm for capacity on Asia-Europe and Transpacific routes. Its dissolution in early 2024 sent shockwaves. Analysts predicted a price war, increased competition, and a boon for shippers. The reality has been a masterclass in corporate strategy.
MSC: The Uncontested, Sovereign Giant
When MSC chose to go solo, it didn’t step back it accelerated its domination. While other carriers were cautious, MSC embarked on a historic fleet expansion, adding record-breaking 2.4 million TEU of newbuild capacity between 2021-2024. Its order book still dwarfs all competitors.
This independence grants MSC three formidable, market-shaping advantages:
- Total Scheduling Autonomy: No need to align rotations or capacity with a partner. MSC can deploy ships where yields are highest, when they choose.
- Yield Management Freedom: It can raise or maintain rates on key lanes without negotiation, setting a de facto price floor that others often follow.
- Strategic Agility: It can quickly pivot networks in response to disruptions (like the Red Sea crisis) or emerging demand, leaving competitors scrambling.
In essence, MSC is no longer just a carrier; it’s a market-maker.
The Gemini Cooperation: Reliability as a Premium Product
Maersk’s response was arguably more strategic. Instead of fighting MSC head-on, it formed the Gemini Cooperation with Germany’s Hapag-Lloyd, effective February 2025. This is not a traditional alliance but a deeper, “network-to-network” integration focused on one mantra: reliability.
What does “reliability” mean in practice?
- Day-Certain Guarantees: Promising delivery within a specific 24-hour window.
- Coordinated Schedules: Seamless handoffs between vessels and inland transport.
- Reduced Blank Sailings: More predictable capacity, but at a cost.
As a Maersk executive privately stated at a recent logistics summit, “We are not competing on being the cheapest. We are competing on being the most predictable. Predictability has a value, and our customers will pay for it.” This shift from a volume game to a value game is the single most important trend defining 2025 freight rates.
Ocean Alliance: The Quiet Disciplinarian
While the CMA CGM-COSCO-Evergreen alliance (Ocean Alliance) remained intact, it used the market turmoil to tighten its own operations. They have reduced publicly announced “blank sailings” but are expertly managing capacity through “slow steaming” and optimized rotations. Their focus is “network efficiency,” a corporate term that translates to running fuller ships on fewer voyages to protect margins.
The Bottom Line: Control Has Replaced Competition
The post-2M world didn’t bring fragmentation; it brought strategic specialization. The market is now split between a sovereign price-setter (MSC), a reliability-focused duopoly (Gemini), and a disciplined volume player (Ocean Alliance). This structure inherently discourages price wars. As one veteran freight broker in Chittagong told me, “Before, if Maersk raised rates, you could check MSC’s 2M partner price. Now, they’re all playing different games, but the result is the same: no one is racing to the bottom.”
Part 2: The Four Pillars Propping Up High Rates in 2025
-
Capacity Discipline: The Art of Artificial Scarcity
Carriers have mastered the fundamental equation of their industry: scarcity equals pricing power. In 2025, this discipline is more calculated than ever.
-
- The “Cape of Good Hope” Bonus: The Red Sea crisis, while a genuine security threat, has been a financial windfall. Rerouting around Africa adds 10-14 days to transit times. This effectively removes 5-10% of global vessel capacity from circulation, creating a perpetual state of tight supply.
- Strategic Blank Sailings: Less announced, more executed. Carriers now use advanced demand algorithms to pre-emptively cancel voyages to prevent rate erosion during soft periods.
- Slow Steaming as Policy: Sailing slower saves fuel (a win for ESG reports) and absorbs excess capacity. It’s an invisible tool for managing supply.
-
Vertical Integration: Owning the Entire Chain
The leading carriers are no longer just moving boxes. They are building fortressed logistics ecosystems.
-
- Maersk’s “Integrator” Model: From buying warehouses (LF Logistics) to developing digital platforms (Maersk.com), Maersk aims to control the entire journey. If you use their ship, their truck, and their warehouse, you get seamless service but you also lose leverage. Your alternative isn’t another carrier; it’s rebuilding your entire supply chain.
- MSC’s Terminal Empire: MSC’s terminal operating arm, TIL, is one of the largest globally. Owning terminals in key transshipment hubs like Colombo or Tangier means priority berthing for MSC ships and congestion for others. This control over port flow is a brutal form of non-price competition.
-
The Data Advantage: Algorithmic Price Optimization
This is the silent game-changer. Carriers now deploy pricing algorithms that analyze datasets shippers can only dream of:
-
- Real-time container utilization across millions of bookings.
- Predictive demand models fed by global economic indicators.
- Historical data on your company’s booking patterns and rate acceptance.
The result is dynamic, surge-based pricing that mirrors Uber or airline tickets. When you log into a carrier’s booking portal, the rate you see isn’t based on a cost-plus model; it’s based on an algorithm’s calculation of what the market will bear at that exact moment for that specific lane. This turns rate negotiation from a quarterly discussion into a real-time, asymmetric battle where the carrier holds all the information cards.
-
The “Green” Premium: Sustainability as a Surcharge
The drive towards decarbonization is real and necessary. However, the 2025 implementation of IMO’s Carbon Intensity Indicator (CII) and the EU’s Emissions Trading System (ETS) for shipping has given carriers a powerful, socially-acceptable rationale for new surcharges. These “green” or “environmental” fees, often ranging from $50-150 per container, are baked into contracts. While the environmental goal is legitimate, the pricing opacity allows carriers to recover costs and add margin under a virtuous banner.
Part 3: Case Study – The Bangladeshi Exporter’s Squeeze
Let’s translate this global architecture into a local reality. Consider “Premium Apparel Ltd.,” a Dhaka-based garment exporter shipping 200 containers monthly to a German retailer.
In 2023 (Pre-2M Breakup):
- Their forwarder booked space on a 2M vessel via Chittagong-Colombo-Rotterdam.
- Rates were volatile but predictable within an alliance framework.
- Space was generally available with two-week advance notice.
In 2025 (New Reality):
- Schedule Chaos: MSC reshuffled its standalone services. Gemini launched new rotations. The reliable weekly cut-off they knew is gone.
- The Reliability Tax: Their buyer now demands tighter delivery windows. To guarantee this, their forwarder must pay a $400 premium per container for Gemini’s “day-certain” service or risk penalties for late delivery.
- The Routing Lottery: Depending on the carrier’s weekly decision on Suez vs. Cape routing, their transit time fluctuates between 28 and 42 days, destroying production and cash flow planning.
- The Digital Wall: When they try to book directly online to save brokerage fees, they face algorithmically generated spot rates that change daily, with no room for negotiation.
The Outcome
Their freight cost as a percentage of the goods’ value has increased from 8% to 14%. This isn’t due to their cargo being heavier or their volumes dropping. It is a direct tax imposed by the re-architected global shipping system. Their story is replicated across Bangladesh’s leather goods, bicycle, and pharmaceutical exporters.
Part 4: What Can Shippers Do? A 2025 Survival Guide
Waiting for a return to 2019 is a strategy for failure. The new architecture is durable. Success requires a new playbook.
For Large Shippers (Global Retailers, Brand Owners):
- Shift from Rate Negotiation to Partnership Modeling: Explore strategic collaborations with a primary carrier. Offer multi-year, volume-based commitments in exchange for locked-in capacity, capped peak surcharges, and data sharing. Become a customer of value, not just a buyer of space.
- Invest in Supply Chain Visibility: You cannot manage what you cannot see. Deploy IoT sensors and advanced tracking to hold carriers accountable to their reliability promises and identify inefficiencies.
- Diversify Geographies and Modes: Explore nearshoring options or regional hubs in Eastern Europe or North Africa. For non-urgent cargo, seriously evaluate the cost-benefit of rail or air-sea combinations.
For SMEs and Exporters (The Most Vulnerable):
- Aggregate to Amplify Power: Join or form shipping cooperatives with other SMEs in your industry or region. Pooling volumes can give you the leverage to negotiate better contracts and secure space.
- Empower Your Freight Forwarder: Your forwarder is your intelligence agency. Partner with one that has strong regional relationships, tech-enabled operations, and the clout to secure allocations. Pay them for their expertise, not just their cheapest quote.
- Master Multi-Routing: Develop a plan B and C for every major lane. Know the alternative services, transshipment hubs, and feeder options. This knowledge prevents panic-buying when your primary service is rolled over.
- Factor Freight into Product Costing: Stop treating freight as a line-item variable. Model at least three freight cost scenarios (base, moderate, peak) into your product’s final cost. Build the resilience into your pricing.
Navigating the Engineered Sea
The message for 2025 is stark: You are no longer just negotiating with sales representatives from shipping lines. You are navigating a highly engineered system built for stability and profitability their stability, their profitability.
The pandemic was a stress test; the aftermath has been a reconstruction. The new shipping reality is one of consolidated power, digital price control, and strategic discipline. For the Bangladeshi exporter, the European retailer, and every business in between, the path forward requires acknowledging this new architecture.
Adaptation is no longer optional. It is the fundamental requirement for survival in a world where the cost of moving goods has been permanently reset by those who control the gears of global trade. The chess pieces have been rearranged. It’s time to learn the new rules of the game. Fast Avkastèr
References
- Alphaliner (2024) Weekly Newsletter: Fleet expansion and orderbook analysis – Q1 2024. Antwerp: Alphaliner.
- BIMCO (2024) Shipping Market Overview and Outlook: Q2 2024. Copenhagen: BIMCO Publications.
- Clarksons Research (2024) Shipping Intelligence Weekly, Vol. 38, No. 22. London: Clarksons Platou.
- Drewry Shipping Consultants (2024) Global Container Forecast Quarterly: Q2 2024. London: Drewry Publications.
- International Transport Forum (ITF) (2024) The Impact of Shipping Alliances on Market Competition and Freight Rates. Paris: OECD Publishing.
- Journal of Shipping and Trade (2024) ‘Vertical integration in container shipping: effects on pricing and service reliability’, Journal of Shipping and Trade, 9(1), pp. 1-24.
- MDS Transmodal (2024) Carrier Vertical Integration and Terminal Ownership: Analysis of Market Power and Port Performance. Chester: MDS Transmodal.
- Notteboom, T. and Rodrigue, J-P. (2024) ‘The restructuring of global container shipping networks post-2M: implications for port hierarchies’, Maritime Economics & Logistics, (Accessed: 4 October 2024).
- Sea-Intelligence ApS (2024) Sunday Spotlight, Issue 623: Capacity Management and Vessel Deployment in the Post-2M Landscape. Copenhagen: Sea-Intelligence.
- The Financial Times (2024) ‘Ocean freight rates: how carriers maintain discipline in a volatile market’, The Financial Times, 15 September.
- United Nations Conference on Trade and Development (UNCTAD) (2023) Review of Maritime Transport 2023: Navigating Stormy Seas. Geneva: United Nations Publications.
- World Bank (2024) Global Logistics and Trade Facilitation Report: Supply Chain Resilience and Costs. Washington, DC: World Bank Publications.